Sinking Funds vs. Emergency Funds in 2026: Which Savings Strategy Do You Actually Need?

Sinking Funds vs. Emergency Funds in 2026: Which Savings Strategy Do You Actually Need?
Saving money is one of the most important habits for building financial stability. However, not all savings serve the same purpose.
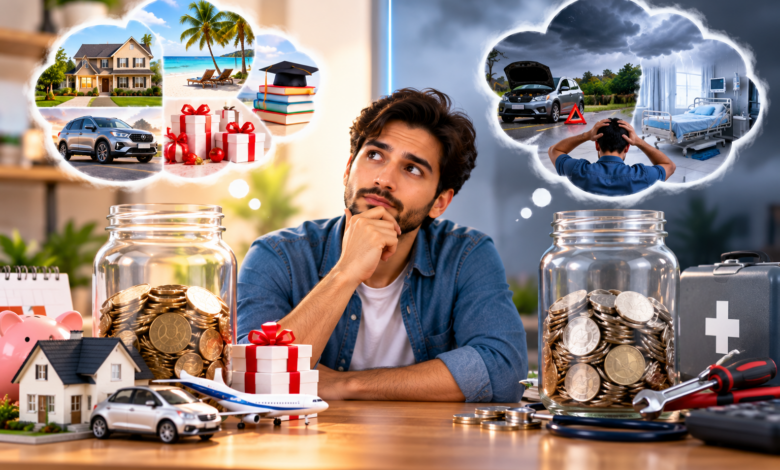
Some expenses are predictable, such as annual insurance premiums, school fees, holiday shopping, or vehicle maintenance. Other expenses arrive unexpectedly, including urgent medical bills, sudden unemployment, or emergency home repairs.
This is where two popular savings strategies become useful: sinking funds and emergency funds.
Although both involve setting money aside, they are designed for different financial situations.
A sinking fund helps you prepare for planned or reasonably predictable expenses. An emergency fund provides financial protection against unexpected and urgent costs.
Understanding the difference can help you organize your budget, avoid unnecessary borrowing, and manage your money more confidently.
In this guide, we explain how sinking funds and emergency funds work in 2026, compare their benefits, provide realistic examples, and show how to build both without overwhelming your monthly budget.
What Is a Sinking Fund?
A sinking fund is money you regularly set aside for a specific future expense.
Instead of paying a large bill from a single month’s income, you gradually save smaller amounts until the money is needed.
For example, imagine you expect to spend $1,200 on annual vehicle insurance.
Rather than finding $1,200 when the bill arrives, you could save $100 every month.
After 12 months, you would have the full amount available.
This approach spreads the financial responsibility across the year and makes large expenses easier to manage.
Sinking funds are especially useful for expenses that do not occur every month but can be anticipated in advance.
Common sinking fund examples
People use sinking funds for many different financial goals, including:
- Annual insurance premiums
- Vehicle maintenance and replacement tires
- Holiday gifts and celebrations
- School fees and educational supplies
- Planned home repairs
- Vacations and travel
- Wedding expenses
- Annual subscriptions and memberships
- Technology replacements
- Property taxes or other periodic obligations
The main feature of a sinking fund is that the money has a clearly defined purpose.
What Is an Emergency Fund?
An emergency fund is money reserved for unexpected, necessary, and often urgent financial situations.
Unlike a sinking fund, an emergency fund is not designed for a particular scheduled purchase.
Its purpose is to provide a financial safety net when something goes wrong.
For example, imagine your employer unexpectedly reduces your working hours.
Your monthly income falls, but you still need to pay rent, purchase groceries, and cover essential transportation.
An emergency fund can help you manage those expenses while you adjust your finances.
Emergency savings may also help cover urgent medical expenses, essential appliance failures, or unexpected travel related to a family emergency.
An emergency fund should generally be accessible without substantial delays or penalties.
Sinking Funds vs. Emergency Funds: Key Differences
Although both strategies involve saving money, they serve different financial purposes.
| Feature | Sinking fund | Emergency fund |
|---|---|---|
| Main purpose | Planned future expenses | Unexpected financial emergencies |
| Expense predictability | Usually known or reasonably expected | Uncertain timing or occurrence |
| Savings target | Based on estimated cost | Based on financial needs and risk |
| Withdrawal timing | When the planned expense occurs | When a genuine emergency arises |
| Number of funds | Multiple categories possible | Usually one main reserve |
| Example | Annual car insurance | Unexpected job loss |
| Savings calculation | Goal amount divided by months | Based on essential expenses and circumstances |
The simplest difference: A sinking fund prepares you for expenses you expect, while an emergency fund protects you against expenses or income disruptions you cannot reliably predict.
Why You May Need Both Savings Strategies
Relying on only one type of savings can create financial challenges.
For example, suppose you have $2,000 in emergency savings.
You then need to pay a predictable $1,000 annual insurance bill.
If you use your emergency fund, you reduce your financial safety net by half.
Now imagine an unexpected medical expense occurs the following month.
Your remaining emergency savings may not be sufficient.
A separate sinking fund for annual insurance could have prevented this situation.
By keeping planned expenses and unexpected emergencies separate, you can protect your emergency reserve while still preparing for upcoming bills.
How Sinking Funds Work: A Practical Example
Consider a household preparing for several expenses throughout the year.
| Savings goal | Target amount | Months available | Monthly savings |
|---|---|---|---|
| Car insurance | $1,200 | 12 | $100 |
| Holiday gifts | $600 | 12 | $50 |
| Vehicle maintenance | $480 | 12 | $40 |
| Annual subscriptions | $240 | 12 | $20 |
| Family vacation | $1,200 | 12 | $100 |
| Total | $3,720 | $310 |
By setting aside $310 each month, the household could accumulate $3,720 over one year.
This assumes every goal starts with a zero balance, contributions remain consistent, and no withdrawals occur before the target dates.
In practice, you may need different savings amounts for expenses due sooner.
For example, if your insurance payment is due in six months instead of twelve, you would need to save $200 monthly to reach a $1,200 target from zero.
How Much Should You Save in an Emergency Fund?
A commonly used emergency savings guideline is to aim for approximately three to six months of essential living expenses.
However, this is a general planning benchmark rather than a universal requirement.
Your appropriate emergency fund size depends on factors such as:
- Monthly essential expenses
- Employment stability
- Household income sources
- Number of dependents
- Health and insurance coverage
- Existing debt obligations
- Availability of financial support
- How quickly you could replace lost income
Someone with stable employment and multiple household income sources may have different needs from a self-employed person with unpredictable income.
Example emergency fund calculation
Suppose your essential monthly expenses are:
| Essential expense | Monthly amount |
|---|---|
| Housing | $900 |
| Groceries | $400 |
| Utilities | $180 |
| Transportation | $220 |
| Insurance and healthcare | $200 |
| Minimum debt payments | $300 |
| Total | $2,200 |
Your emergency savings targets might be:
1 month
$2,200
3 months
$6,600
6 months
$13,200
Illustrative targets based on $2,200 in essential monthly expenses.
If saving $6,600 feels unrealistic, you can begin with a smaller amount and gradually increase it.
The goal is to build a financial buffer that fits your circumstances.
Sinking Fund Calculator: How Much Should You Save Monthly?
The basic sinking fund formula is:
\[ \text{Monthly Savings}=\frac{\text{Target Amount}-\text{Current Savings}}{\text{Months Remaining}} \]
For example, if you want to save $1,800 for a future expense, already have $300 saved, and have 10 months remaining:
($1,800 − $300) ÷ 10 = $150 per month.
You would need to save $150 each month to reach your goal, assuming no interest earnings or changes to the target.
Interactive savings calculator
Use this calculator to estimate how much you need to save for a planned expense.Target savings ($)Already saved ($)
Months until expense
10
Amount still needed
$1,500.00
Save each month
$150.00
Estimates assume equal monthly contributions without interest, fees, or changes in the expected expense.
How to Start a Sinking Fund: Step-by-Step Guide
Building a sinking fund does not require a high income.
The most important steps are identifying upcoming expenses and saving consistently.
Step 1: Identify irregular expenses
Review your previous year’s spending.
Look for bills and purchases that occur quarterly, semiannually, or annually.
Examples include insurance renewals, vehicle registration, and school expenses.
Step 2: Estimate the total cost
Determine how much each expense is likely to cost.
Use previous bills, current prices, or realistic estimates.
If prices may change, consider including a reasonable buffer.
Step 3: Set a deadline
Identify when you will need the money.
The number of months available determines how much you should save regularly.
Step 4: Calculate monthly contributions
Divide the amount still needed by the number of months remaining.
If the required contribution is too high, consider adjusting the goal, extending the timeline where possible, or reducing other discretionary expenses.
Step 5: Separate your savings
You can use separate savings accounts, digital budgeting categories, or a spreadsheet.
The important thing is to know how much belongs to each goal.
Step 6: Automate contributions
If possible, schedule automatic transfers after receiving your income.
This can help make saving more consistent.
Step 7: Review your progress
Check your sinking funds periodically.
Update the target amounts if costs or deadlines change.
How to Build an Emergency Fund From Scratch
Building emergency savings may take time, especially when essential expenses consume most of your income.
A gradual approach can make the process more manageable.
Start with a small initial goal
Instead of immediately targeting several months of expenses, begin with an achievable amount.
For example, your first goal might be $100, $250, or $500, depending on your circumstances.
Choose a safe and accessible location
Emergency savings are generally best kept somewhere secure and readily accessible.
A suitable insured savings account may be an option, depending on your country and available banking services.
Avoid placing money needed for immediate emergencies into investments that can experience significant short-term losses or withdrawal restrictions.
Contribute consistently
Even small regular contributions can build over time.
For example, saving $25 per week would total $1,300 over 52 weeks, excluding interest.
Use occasional extra income carefully
Bonuses, refunds, gifts, or additional freelance income may help you build emergency savings faster.
However, make sure essential obligations and any applicable taxes are covered first.
Replenish the fund after withdrawals
If you use emergency savings, make rebuilding the balance a priority when your finances allow.
This helps restore your financial safety net.
Should You Build an Emergency Fund or Sinking Fund First?
The answer depends on your immediate financial needs.
If you have no emergency savings, establishing a small financial buffer may be a useful first step.
However, you should not ignore essential expenses that are already approaching.
For example, if your annual insurance bill is due in two months, saving for that known expense may be necessary to avoid a missed payment.
A balanced approach may involve contributing to both funds.
You could direct a larger portion of available savings toward your emergency fund while setting aside smaller amounts for upcoming predictable bills.
Once you have an initial emergency buffer, you can adjust your contributions according to your financial priorities.
Where Should You Keep Sinking Funds and Emergency Funds?
The best savings location depends on when you need the money and how easily you must access it.
| Savings option | Sinking fund | Emergency fund |
|---|---|---|
| Regular savings account | Often suitable | Often suitable |
| High-yield savings account | May be suitable | May be suitable |
| Separate bank subaccounts | Useful for organizing goals | Useful for keeping money separate |
| Fixed-term deposit | May suit longer planned goals if maturity aligns | Often less suitable for immediate access |
| Volatile investments | Generally unsuitable for near-term goals | Generally unsuitable for emergency reserves |
Savings products, deposit insurance protections, withdrawal restrictions, and interest rates vary by country.
Before opening an account, compare fees, accessibility, safety, and applicable deposit protection.
Can You Use an Emergency Fund for a Planned Expense?
Generally, it is better to keep emergency savings reserved for unexpected necessities.
Using emergency money for a planned vacation, routine insurance renewal, or nonessential purchase reduces the amount available for genuine emergencies.
However, financial circumstances are not always straightforward.
If a planned expense is essential and you have no other available funds, you may need to prioritize immediate needs.
For example, paying an essential housing-related bill may be more urgent than maintaining an untouched savings balance.
If you use emergency savings, create a realistic plan to rebuild the fund when possible.
Can a Sinking Fund Become an Emergency Fund?
Yes, money in a sinking fund can sometimes be redirected to an emergency if necessary.
For example, suppose you have saved $1,500 for a future vacation.
If you unexpectedly lose your job, you may decide to postpone the vacation and use the money for essential living expenses.
This can be a reasonable financial decision.
However, regularly using sinking funds for unrelated expenses may make it difficult to achieve planned savings goals.
The purpose of separate funds is to improve organization, not to create inflexible rules.
Sinking Funds for Freelancers and Self-Employed Workers
Freelancers and self-employed individuals often face irregular income and business expenses.
Sinking funds can help them prepare for predictable costs such as software renewals, equipment replacement, professional memberships, and annual business expenses.
They may also need to set aside money for taxes, depending on local requirements.
Tax reserves should be calculated separately and should not be treated as optional savings.
Emergency funds can be particularly important for people whose income varies significantly from month to month.
A self-employed worker may need a larger financial buffer if replacing lost income would take considerable time.
When income is irregular, saving a percentage of each payment received may be easier than committing to a fixed monthly amount.
Common Sinking Fund Mistakes to Avoid
One common mistake is creating too many savings categories at once.
Although detailed planning can be useful, managing dozens of separate funds may become unnecessarily complicated.
Another mistake is underestimating future costs.
For example, a vehicle maintenance fund based only on oil changes may not be sufficient for tires or larger repairs.
Some people also forget to update their sinking funds when prices increase or payment deadlines change.
Finally, saving for optional purchases while neglecting urgent bills or expensive debt may create financial problems.
Sinking funds should support your broader financial priorities.
Common Emergency Fund Mistakes to Avoid
Emergency savings can also be mismanaged.
One mistake is treating the fund as money available for routine discretionary spending.
Another is keeping emergency money in an account that is difficult to access quickly.
Some individuals invest their entire emergency reserve in volatile assets, exposing money needed for urgent expenses to market losses.
Others set an unrealistic savings target and become discouraged when progress is slow.
A more practical approach is to build emergency savings gradually while maintaining access to funds when needed.
How Inflation Affects Sinking Funds and Emergency Funds
Inflation can increase the amount of money required for future expenses.
For example, if an annual insurance premium costs $1,000 today, it may cost more when the next renewal arrives.
Similarly, rising housing, food, or transportation costs can increase the amount needed for an emergency fund.
Review your savings targets periodically rather than assuming they will remain appropriate indefinitely.
For sinking funds, update estimated expenses as new pricing information becomes available.
For emergency funds, recalculate essential monthly expenses when your household budget changes significantly.
How to Manage Multiple Savings Goals Without Feeling Overwhelmed
Managing several savings goals can seem complicated, but a simple priority system can help.
Start with essential obligations that have fixed deadlines.
Next, consider building an initial emergency reserve.
After that, allocate available money toward other planned expenses and longer-term financial goals.
You do not necessarily need a separate bank account for every sinking fund.
A spreadsheet or budgeting app can help track different categories within one savings account, provided the total recorded savings do not exceed the actual account balance.
Reviewing your goals once a month may be sufficient for most households.
Sinking Funds vs. Emergency Funds: Which Is Better for Financial Stability?
Neither strategy is universally better.
Sinking funds reduce the risk that predictable expenses will disrupt your monthly budget.
Emergency funds reduce the financial impact of unexpected events.
Together, they provide a more complete approach to managing financial uncertainty.
For example, a sinking fund can help you pay annual vehicle insurance without using a credit card.
An emergency fund can help you cover essential expenses after an unexpected job loss.
Both strategies may reduce dependence on expensive borrowing, although neither can guarantee protection against every financial difficulty.